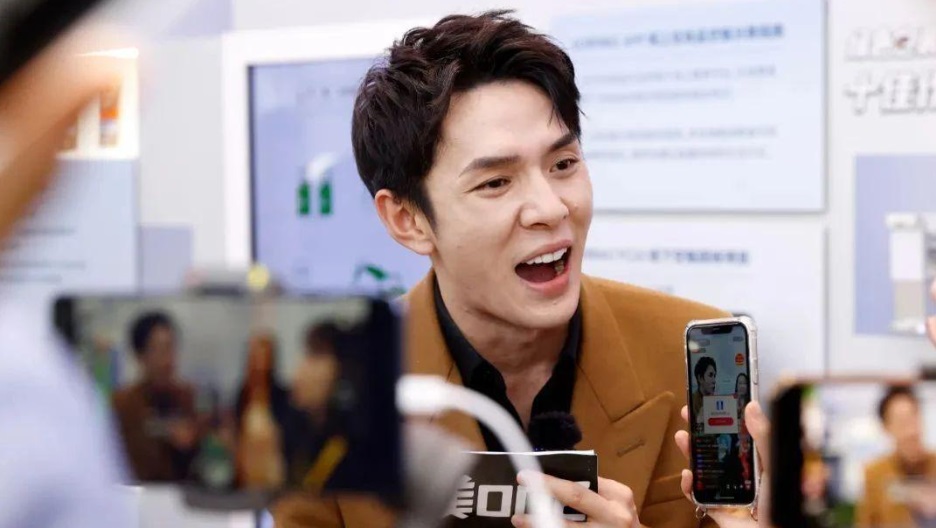
Live commerce in China has stopped being a marketing tactic. It is now a distribution channel with its own budget lines, its own headcount, and its own place in a brand’s annual planning cycle. In 2025, live commerce transactions reached roughly RMB 5.26 trillion, with penetration climbing to about 32.9% of the overall online shopping market, according to industry tracking cited by Huaon. In the first half of 2026, live commerce retail sales broke through RMB 1 trillion on their own, growing 6.5% year on year. That is not novelty spending. That is a third of a market the size of China’s online retail sector running through livestreams.
What makes 2026 different from the boom years of 2019-2021 is not the size of the number. It is who is generating it. TikTok’s domestic sibling Douyin, along with Kuaishou and Taobao Live, spent years building an economy around a handful of celebrity hosts who could move tens of millions of RMB in a single evening. That model still exists, but it no longer sets the pace. Brand-owned livestream accounts, what the Chinese trade press calls 店播 (dianbo, “store broadcasting”) as opposed to 达播 (dabo, “influencer broadcasting”), now generate more than half of total live commerce GMV. The channel that used to be about renting someone else’s audience has become a channel about building your own.

From novelty to infrastructure
The early years of live commerce were built on scarcity and spectacle. A brand paid a top-tier host a placement fee plus commission, got a slot in a packed selling calendar, and watched inventory move in a two-hour window. It worked, but it was rented shelf space. The moment the host moved to another platform or fell out of favour with regulators, the sales history went with them. Several China-based brand teams learned that lesson the hard way when leading hosts were suspended or taxed heavily in past years, taking entire quarters of revenue with them.
What replaced that dependence is not glamorous, but it is durable. Professional MCN-run studios now operate on behalf of brands rather than around individual personalities, staffing rotating hosts, script writers, and control-room operators who run six, eight, sometimes twelve hours of continuous broadcast a day. Growth has also cooled from the explosive 245.9% rates of the earliest boom years to a steadier band closer to 18% annually through 2026, according to trade analysis from Tencent News. That is what a maturing channel looks like: less spectacular, more predictable, and considerably easier to plan a budget around.
Why brands are choosing to broadcast themselves
The economics tell most of the story. A top-tier KOL commission can run 20-40% of GMV on top of a fixed placement fee, and that fee has to be renegotiated for every campaign. A brand-run studio has fixed costs: staff salaries, a physical or virtual set, camera and lighting equipment, and platform advertising to drive traffic to the room. Once that infrastructure exists, the marginal cost of an extra hour of broadcast is low, and every yuan of margin stays with the brand rather than being split with an intermediary.
Control matters as much as cost. A host who does not work for the brand can misstate a formulation, promise a discount that finance has not approved, or simply have an off night. A brand’s own hosts, trained on product knowledge and pricing rules, do not carry that risk. Chinese commentary on the 2026 season describes the shift as content moving from “叫卖式” (hawker-style shouting) toward more structured, trust-building formats: ingredient walkthroughs, factory-origin livestreams, and Q&A sessions that resemble a customer service call more than a sales pitch. That format only works if the person on camera actually represents the brand.
There is also a data argument. Every viewer who lands in a brand’s own livestream room, follows the account, or joins its member programme becomes an asset the brand can retarget later without paying platform traffic costs again. Chinese analysts frame this as a shift from being a “tenant” renting audience attention from platforms to becoming a “landlord” who owns a slice of it. For a foreign brand trying to build repeat purchase behaviour in a market where trust is earned slowly, that owned relationship is worth more than a single strong sales night.
What this means for how a foreign brand should staff up
The practical consequence is uncomfortable for brands used to treating livestreaming as an occasional campaign line item. A serious Douyin or Tmall presence in 2026 increasingly requires a standing livestream operation: at minimum a rotating pair of trained hosts, someone managing the broadcast schedule and script, and a person watching real-time comments and conversion data during every session. This is closer to running a small broadcast studio than to booking a few sponsored posts, and it needs to be budgeted, staffed, and reviewed the way any other ongoing sales channel would be.
That does not mean top-KOL collaborations disappear. They remain useful for reach spikes around new product launches or major shopping festivals, where a large existing audience can compress months of discovery into a single day. But treating a celebrity host as the entire live commerce strategy is now the exception rather than the rule among brands that are actually growing share. The steadier revenue base sits with the brand’s own room, running most days of the year, feeding traffic back into the brand’s Tmall store and other owned channels rather than depending on one person’s calendar.
For a foreign brand entering or expanding in China, the sizing question is no longer “should we do a livestream campaign.” It is closer to “who runs our livestream desk, how many hours a week does it broadcast, and what does that cost against the margin it protects by not paying a top host’s commission.” Brands that answer that question early tend to build the muscle before a competitor locks up the audience. Brands that keep treating live commerce as an occasional stunt are increasingly buying attention at a premium in a channel where their rivals already own the room.
Sources: 2026年中国直播电商行业发展现状及前景展望, Huaon Industry Research; 2026年上半年直播电商零售额破万亿元, ZAKER News; 2026,直播电商”卷”向何处?, Tencent News
Matt Sun is Chief Ecommerce Officer at EAC (Ecommerce China Agency). He has spent the past decade building and running Tmall, JD, and Douyin store operations for international brands entering China, and has sat inside live commerce control rooms during 618 and Double 11 broadcasts that generated more single-day revenue than some clients’ entire prior-year China turnover. He argues that most foreign brands underinvest in their own livestream desk and overpay for one-off KOL bookings that leave nothing behind once the broadcast ends. If your team needs help deciding whether to build, outsource, or hybridise your live commerce operation, get in touch with EAC.