In late 2023, Alibaba launched a new app called the “Taobao Exchange Market” (宝购汇市 — Bǎogòu Huìshì). The stated objective was direct: offer prices lower than Taobao, Tmall, and Pinduoduo. This was an unusual move for a company that operates the most successful premium e-commerce platform in China — publicly targeting lower price points to compete in a segment where rival Pinduoduo has built dominance.
The Taobao Exchange Market initiative reflects a broader strategic pressure Alibaba faces in the Chinese e-commerce landscape and provides useful insight for brands thinking about how the platform competitive dynamics affect their China distribution strategy.
What the Taobao Exchange Market Is
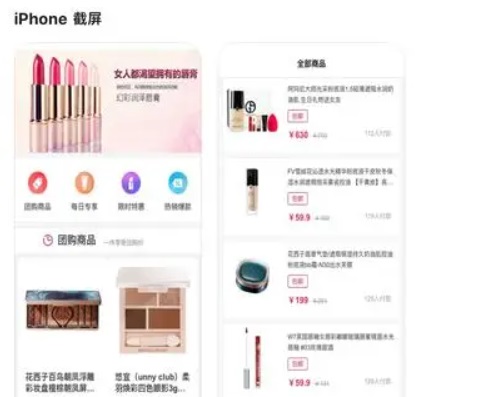
The Taobao Exchange Market is a standalone mobile app, separate from the main Taobao and Tmall apps. It operates as a price-discovery and low-cost purchasing platform: sellers list products at discounted prices, often representing surplus inventory, factory-direct goods, or products from sellers looking to clear stock quickly. The marketplace aggregates these offers and allows price comparison across categories.
The concept is not entirely new — similar “deal discovery” and surplus marketplace models have existed in China for years. What makes this launch notable is that it comes directly from Alibaba, the company that built and defended the premium e-commerce brand positioning of Tmall through years of careful curation and brand partner investment.
Why Alibaba Is Moving Down-Market
Pinduoduo’s Disruption
Pinduoduo (拼多多) launched in 2015 with an explicitly value-oriented positioning: group buying, deeply discounted prices, and aggressive couponing targeting price-sensitive consumers in lower-tier Chinese cities. The platform grew rapidly by serving consumers who were either excluded from Tmall’s brand partner model or unwilling to pay Tmall prices for products they could find cheaper elsewhere.
By 2023, Pinduoduo’s monthly active users surpassed Taobao’s for the first time. Its international arm, Temu, was expanding aggressively in Western markets. Alibaba had not effectively contested Pinduoduo’s low-price positioning for years, and the market share loss had become significant enough to require a direct response.
The Price Sensitivity Shift After COVID
Chinese consumer sentiment shifted measurably after the 2022-2023 COVID lockdown period. Surveys from 2023 and 2024 consistently show an increase in price consciousness among Chinese consumers across income tiers — including middle-class consumers who had previously been comfortable paying premium prices on Tmall. This is sometimes called “consumer downgrade” (消费降级 — xiāofèi jiàngjí) in Chinese media: not poverty-driven, but a behavioral recalibration toward value-seeking even when income levels have not declined. Alibaba recognized that its premium positioning, which had been an asset in the 2015-2021 period, was creating a vulnerability as consumer preferences shifted toward value.
Alibaba’s Structural Challenge
The difficulty for Alibaba in launching a low-price marketplace is a classic brand cannibalization dilemma. If the Taobao Exchange Market succeeds in attracting price-sensitive buyers, it risks drawing them away from Taobao and Tmall rather than exclusively from Pinduoduo. Alibaba must build a value proposition compelling enough to compete with Pinduoduo while not undermining the premium marketplace brands that generate significantly higher GMV per transaction and stronger advertiser revenue.
This tension has not been fully resolved as of 2025. The Taobao Exchange Market remains a relatively small part of Alibaba’s overall commerce portfolio. The primary competitive response to Pinduoduo has come through Taobao and Tmall’s own pricing initiatives — an “RMB 100 billion subsidy” campaign on Taobao in 2023, broader coupon and price-reduction programs — rather than through the standalone exchange market app.
What This Means for Brand Sellers on Chinese Platforms
Pricing Pressure Is Increasing Across All Platforms
The broader competitive response to Pinduoduo — including Alibaba’s subsidy programs, JD’s “price matching” guarantee campaigns, and Douyin’s growing e-commerce presence — has increased pricing pressure on brands selling through Chinese e-commerce platforms. Platforms are competing on price to consumers, which creates pressure on the seller side to accept lower margins or provide deeper promotional discounts to remain competitive in search and recommendation algorithms.
For international brands entering China, this environment requires clear thinking about price positioning before platform selection. Brands that need to maintain a premium price to protect global pricing consistency (luxury goods, flagship electronics) should concentrate on Tmall’s brand partner program where the premium environment is maintained. Brands with more pricing flexibility may benefit from the volume-driven models available on Taobao, JD, or emerging discount channels.
Platform Diversification Is More Important Than Ever
The emergence of Pinduoduo as a genuine competitor to Alibaba, and Alibaba’s responses including the Taobao Exchange Market, signals that no single platform dominance is permanent in Chinese e-commerce. Brands that concentrated their entire China e-commerce operation on Tmall in 2018-2020 found themselves exposed when Douyin’s live commerce began capturing significant consumer attention in 2021-2022. Today, a resilient China e-commerce strategy distributes presence across Tmall (premium/brand equity), JD (product quality signal and logistics reliability), Douyin (content-driven discovery and live commerce), and potentially Pinduoduo or its equivalent for volume-driven categories.
For more on China e-commerce platform strategy, see EAC’s Tmall management guide and our overview of Douyin e-commerce.
FAQ: The Taobao Exchange Market and China E-Commerce Competition
How significant is the threat from Pinduoduo to Alibaba’s core business?
The threat is real and has been acknowledged by Alibaba’s leadership in public communications since 2022. Pinduoduo’s market capitalization briefly surpassed Alibaba’s in late 2023 — a development that would have been considered impossible by most analysts five years earlier. In terms of GMV, Alibaba (Taobao + Tmall) remains larger than Pinduoduo, but the GMV per transaction is much lower on Pinduoduo, meaning Pinduoduo is growing its transaction volume faster while Alibaba maintains higher average order values. The competitive dynamic is: Alibaba retains the brand-conscious, higher-income consumer and the international brand partner ecosystem; Pinduoduo captures the value-seeking consumer and the factory-direct seller ecosystem. These two segments of the Chinese e-commerce market are not shrinking — China’s e-commerce market is large enough for multiple platforms to grow simultaneously. But Alibaba’s share of total new e-commerce GMV growth has declined as Pinduoduo and Douyin have captured disproportionate shares of incremental growth. Alibaba’s long-term strategic response involves restructuring into separate business units (announced in 2023), investing in AI infrastructure, and international expansion through Alibaba International. The Taobao Exchange Market is one small tactical element of a larger strategic repositioning.
Source: Alibaba FY2024 annual report; Pinduoduo FY2024 earnings releases; Bloomberg Intelligence China E-Commerce Platform Analysis 2024; Morgan Stanley China Internet Sector Report 2024
Should brands sell on Pinduoduo as well as Tmall?
The answer depends on the brand’s category, price positioning, and China market goals. Pinduoduo is the right channel for brands with: low-to-mid price point products (under 200 RMB per unit), high price sensitivity in the target consumer, products where brand equity is less central to the purchase decision (commodity food, household consumables, tools and accessories), and sufficient volume to absorb Pinduoduo’s low-margin environment. Pinduoduo is the wrong channel for: luxury and premium brands (the platform’s positioning undermines premium brand equity — selling luxury products on Pinduoduo creates a brand inconsistency that erodes the brand’s positioning on Tmall), brands that compete primarily on innovation and quality differentiation (Pinduoduo’s buyer base is more price-sensitive and less brand-loyal), and brands in categories where counterfeit risk is high (Pinduoduo has faced counterfeit concerns, and premium brands appearing on Pinduoduo risk being associated with grey market or fake product activity). Many international brands start with Tmall, test JD, and evaluate Pinduoduo only if they have specific lower-price SKUs that can be cleanly segregated from their flagship offering without brand damage.
Source: EAC Ecommerce China Agency client platform analysis (2024); Tmall vs. Pinduoduo brand positioning case studies; iResearch China Multi-Platform E-Commerce Brand Strategy Report 2024
Thinking through your China platform strategy? Get a free audit from our team. For more on Tmall and multi-platform management, see EAC’s Tmall services and our guide to selling on Taobao.
Harry Huang, E-Commerce Performance Manager at EAC Ecommerce China Agency. Harry’s job is simple: make your China store profitable, fast. He runs platform accounts on Tmall, JD, and Douyin with one metric in mind — revenue per RMB spent. No wasted cycles, no bloated retainers.
His approach is diagnostic. He identifies the exact conversion blockers — pricing, listing copy, promotion timing, traffic mix — fixes them in order of impact, and moves to the next lever. Brands working with Harry typically see their first measurable ROI improvement within 30 days.
Harry has managed accounts across health, beauty, consumer tech, and lifestyle categories. He thinks in dashboards, acts on data, and delivers results ahead of schedule. If you need execution with accountability, Harry is who you call.
Ready to improve your China e-commerce ROI? Get a free audit from our team.
Connect with Harry Huang: ecommercechinaagency.com/author/philip/